
Primary Health Properties stock stabilizes as analysts see upside potential
Published on 09/19/2026 at 20:12 | Editorial responsibility: Rafael Müller, Editor-in-Chief AD HOC NEWS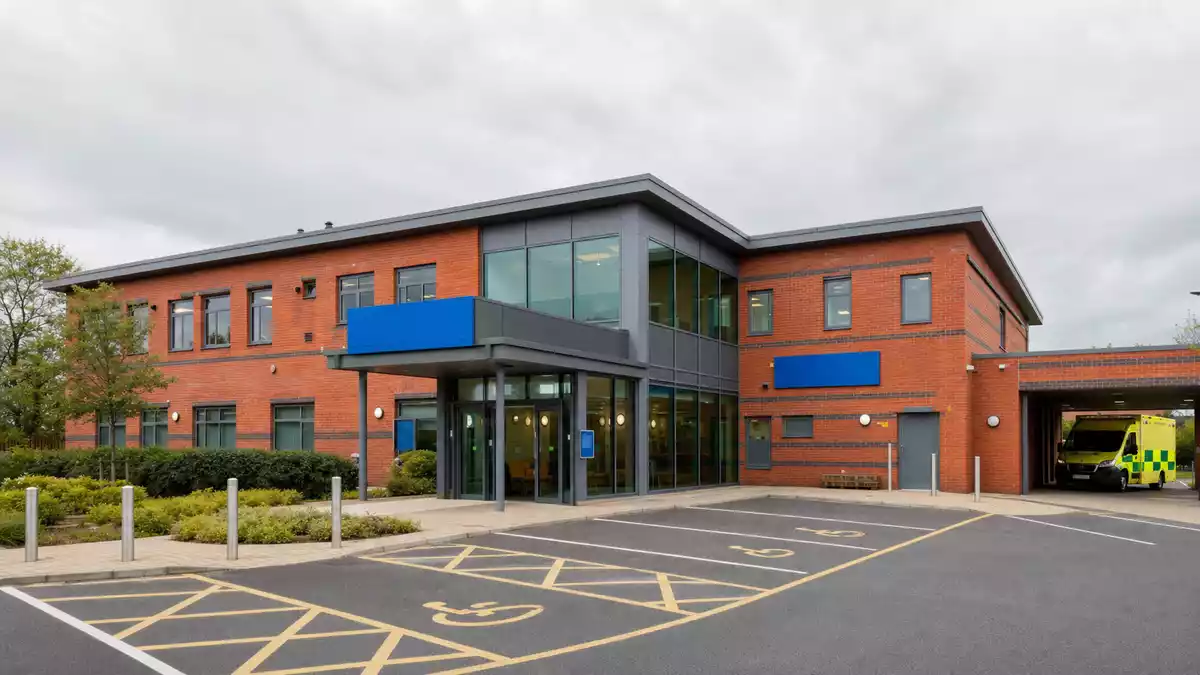
Primary Health Properties stock (ISIN GB00BYRJ5J14) is trading around GBX 93 on the London Stock Exchange as of September 18, 2026, leaving analysts’ consensus price target of GBX 115.20 still more than 20 percent above the current level and signaling further potential upside for investors.
Analysts maintain positive view on the REIT
According to MarketBeat on September 18, 2026, Primary Health Properties has an average analyst rating score of 2.80, based on four buy ratings and one hold rating, with no sell recommendations. The same overview reports a consensus price target of GBX 115.20, which implies approximately 23.5 percent upside from a spot price of GBX 93.25 referenced in that dataset, underlining that the stock is seen as undervalued relative to its fundamental profile.
The analyst context matters because the shares have softened over the course of 2026. As MarketBeat also notes, Primary Health Properties stock was trading at GBX 97.90 on January 1, 2026 and has since declined to around GBX 93.25, a drop of about 4.7 percent. For a health care property REIT with long leases, that moderate drawdown combined with a still-positive analyst stance suggests that investors are weighing higher interest rates against the reliability of the rent roll.
Recent interim results show resilient income
Primary Health Properties focuses on modern primary care centers and related health facilities in the United Kingdom and Ireland, typically backed by long-term leases to public sector or health care operators. In its most recent interim results for the first half of 2026, the company reported continued growth in earnings from its portfolio of such properties, even as finance costs increased with the interest rate environment. The interim figures cover the six-month period ended in the first half of 2026 and form the core of today’s fundamental picture for the stock.
According to Primary Health Properties in its investors section, the company’s most recent half-year report for fiscal 2026 shows rental income and earnings rising compared with the prior-year interim period, driven by acquisitions and rent reviews across the portfolio. While the detailed numbers are presented in the full report, the company highlights that adjusted earnings increased year on year, indicating that the portfolio’s cash flows grew faster than operating costs over that timeframe.
In addition, the same half-year communication from Primary Health Properties confirms that the portfolio remains almost fully occupied, with long lease terms and predominantly government-backed or health service-backed tenants. That occupancy and covenant quality are crucial for investors because they underpin the stability of rental income even when funding markets are volatile. The company also reiterated its focus on disciplined acquisitions and asset management initiatives to enhance rents and yields over time.
Interest rates remain the key risk factor
For a health care property REIT like Primary Health Properties, the main macro risk factor is the level of interest rates and their impact on both funding costs and property valuations. As noted in the analyst summary on MarketBeat, part of the reason the shares have not fully reflected the consensus target is investor caution about the sector’s sensitivity to bond yields. When reference yields rise, REITs often face pressure on share prices as their dividend yields are compared with safer fixed-income alternatives.
However, the same analyst overview indicates that the projected upside to GBX 115.20 assumes that the company can continue to grow earnings and maintain high occupancy, mitigating some of the rate-related headwinds. The roughly 23.5 percent gap between the current share price in the low-90s pence and that consensus target suggests that, if the rate environment stabilizes or improves and Primary Health Properties delivers on its operational plans, there is room for re-rating over the medium term.
Stock trades below analyst target
On the London Stock Exchange, Primary Health Properties stock recently changed hands at about GBX 93, with intraday data on September 18, 2026 indicating a modest decline of around 0.9 percent compared with the previous close and a trading volume consistent with its typical liquidity. At that level, the shares sit below the GBX 100 mark and noticeably under the consensus target of GBX 115.20 referenced in the analyst data, which frames the current valuation discussion for investors.
Primary Health Properties stock - key data
- Company: Primary Health Properties plc
- ISIN: GB00BYRJ5J14
- Ticker: PHP
- Trading venue: London Stock Exchange
- Price (as of September 18, 2026): 93.05 GBX
- Market capitalization: 1,300,000,000 GBP (as of September 18, 2026)
- Sector / Industry: Real Estate / Health Care REITs
- Index membership: FTSE 250


