Almonty's Sangdong Ramp-Up Meets a Courtroom Detour and a Korean Listing Ambition
Published on 11/21/2026 at 03:01 | Editorial boerse-global.de
Almonty Industries is discovering that building a tungsten mine is only half the job. The other half is proving it can turn a first shipment into a repeatable business — and doing so while a Canadian lawsuit, fresh analyst cuts and a planned Korean listing all compete for investors' attention.
The stock's recent slide tells part of that story. Shares fell 15% to €5.87 in one session, following a 16% decline the prior day. Behind the selling is a legal dispute: Deutsche Rohstoff disclosed on 11 November that it has sued Almonty in Canada for roughly USD 67 million, citing alleged breaches of contract. The claim covers 3.5 million conversion shares plus repayment of debt. Almonty has filed its own suit against Deutsche Rohstoff, and the two proceedings have been consolidated.
What the analysts did with their targets
The re-rating has been swift. Sphene Capital trimmed its price target on 16 November to USD 22.40 from USD 26.40, keeping a buy rating. Stifel had cut its own target to USD 18 from USD 21 on 13 November, also maintaining a buy. GBC AG, for its part, lowered its 2026 revenue forecast to USD 125.9 million while holding its buy recommendation — and it still expects Sangdong to be in commissioning and ramp-up through the fourth quarter of 2026. Its reduced 2027 estimate stands at USD 520.0 million, with 2028 at USD 1.19 billion.
Those are forecasts, not booked revenue. The gap between what GBC expects this year and what it projects for later years shows how much of the story still depends on execution at Sangdong.
A first container, and the question of the second
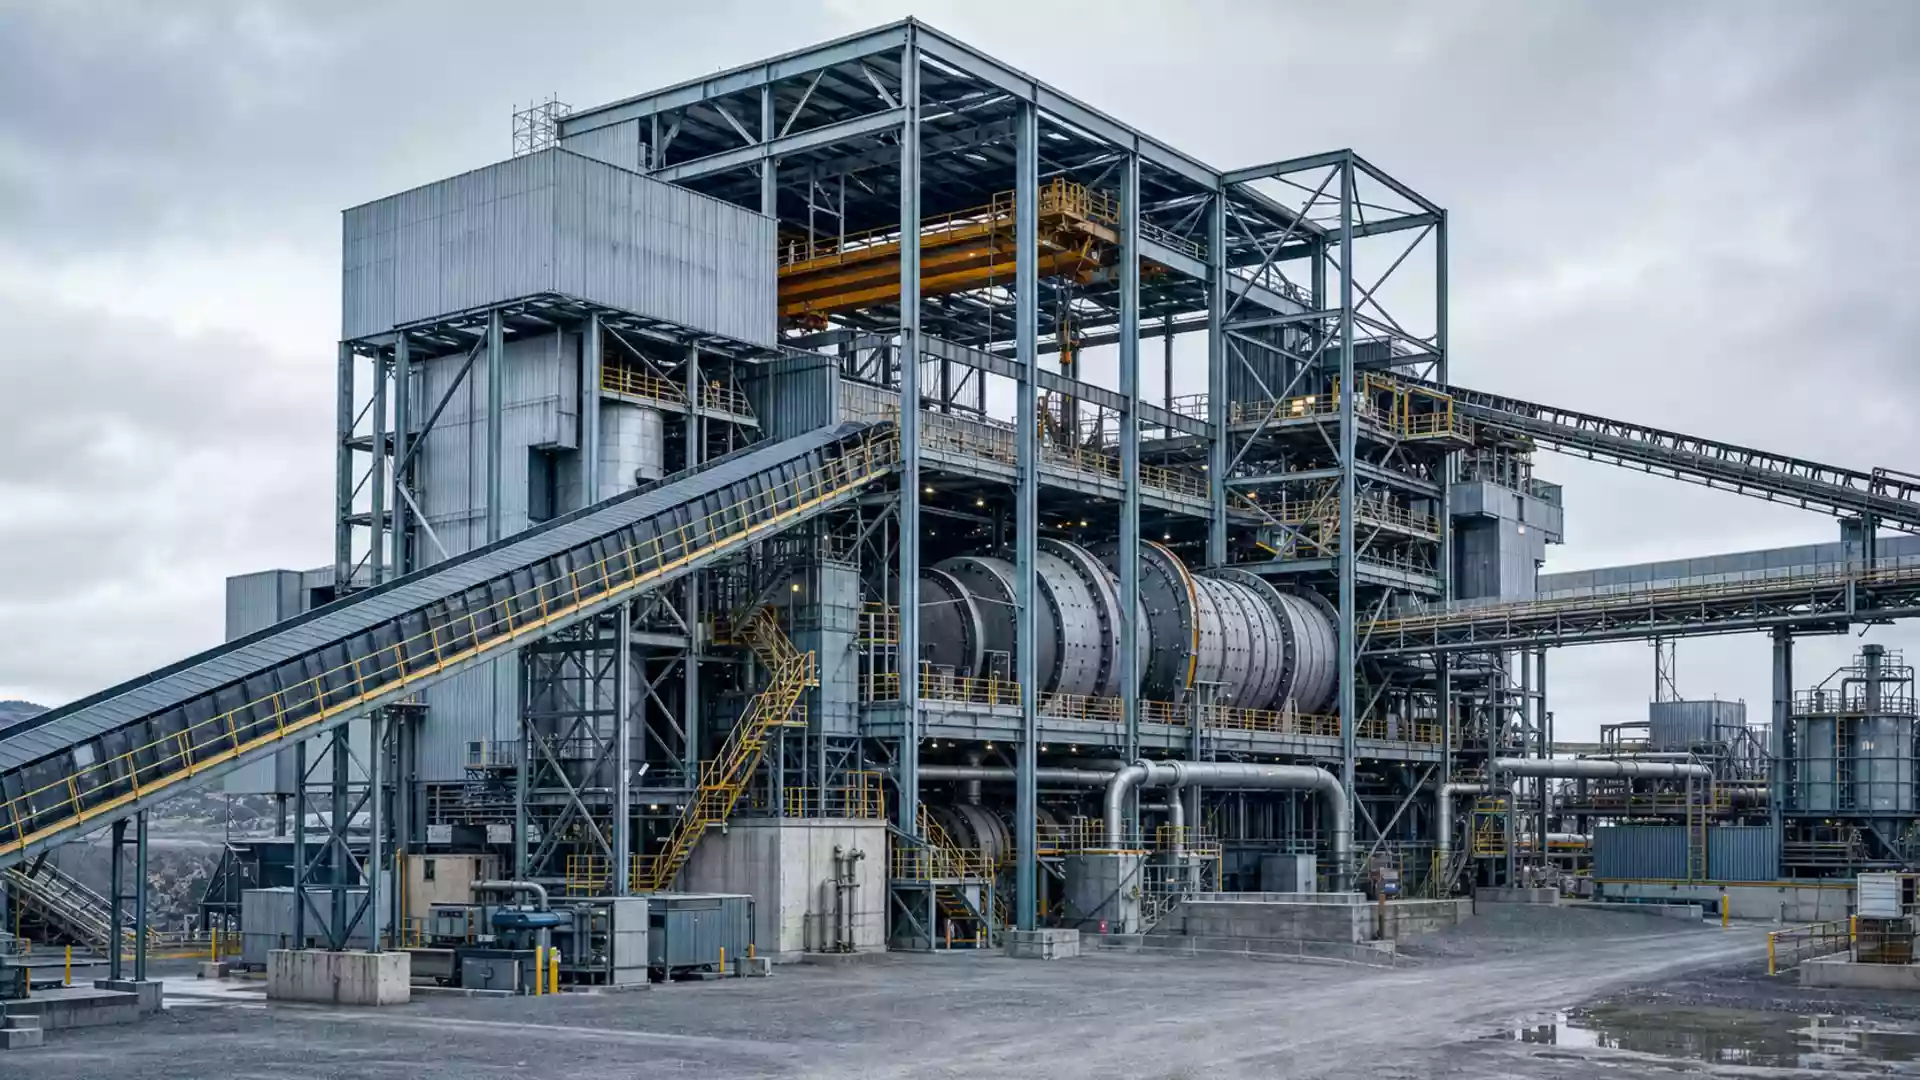
On the operational side, Almonty produced its first tungsten concentrate at Sangdong in September. After the close of the third quarter of 2026, the first container of concentrate was loaded in Busan for overseas shipment. That documents a first step from production to dispatch. What matters more for judging the business is whether the company can repeat the sequence regularly.
Should investors sell immediately? Or is it worth buying Almonty?
The balance sheet offers some room to maneuver. Almonty reported cash of C$1.15 billion as of the end of September. That figure describes the financial headroom the company carried into the ramp-up; it does not answer the operating question of how much ore Sangdong can reliably produce and prepare for shipment.
For the third quarter of 2026, Almonty posted revenue of C$41.9 million and adjusted EBITDA of C$14.6 million. Net income came in at C$50.2 million — a figure that included non-cash gains of C$47.9 million from the revaluation of derivatives and warrants.
A European benchmark, and its limits
Diamond Equity Research put the European price for tungsten APT at around USD 2,650 per MTU on 17 November, and in the same note assigned an illustrative value of USD 18.40 per share. The distinction matters: one number describes a market price, the other is the output of a valuation. Neither tells us the price at which Almonty will actually sell its concentrate.
A European reference price helps frame the economic opportunity. Repeatable production and further shipments would be the more tangible yardstick for how far Almonty has come toward a steady delivery business.
Separately, the company is pursuing a secondary listing on the Korea Exchange. The move is subject to approval by the exchange and regulators, suitable market conditions and compliance with securities-law requirements.
For now, the operating anchor is the current fourth quarter of 2026. The next updates will be watched for one thing above all: whether the first loaded container is followed by others, and whether Almonty reports progress on the consistency of production.
Ad
Almonty Stock: New Analysis - 21 November
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.