Almonty's Sangdong Restart Delivers First Cargo in 30 Years as B. Riley Trims Target to $20
Published on 11/04/2026 at 04:21 | Editorial boerse-global.de
Almonty has checked two very different boxes in the space of a week: it shipped tungsten concentrate out of Sangdong for the first time in more than three decades, and it closed a US$129.375 million equity raise. Neither event, on its own, settles the question investors actually care about — whether the mine's expansion will unfold on the schedule management has laid out.
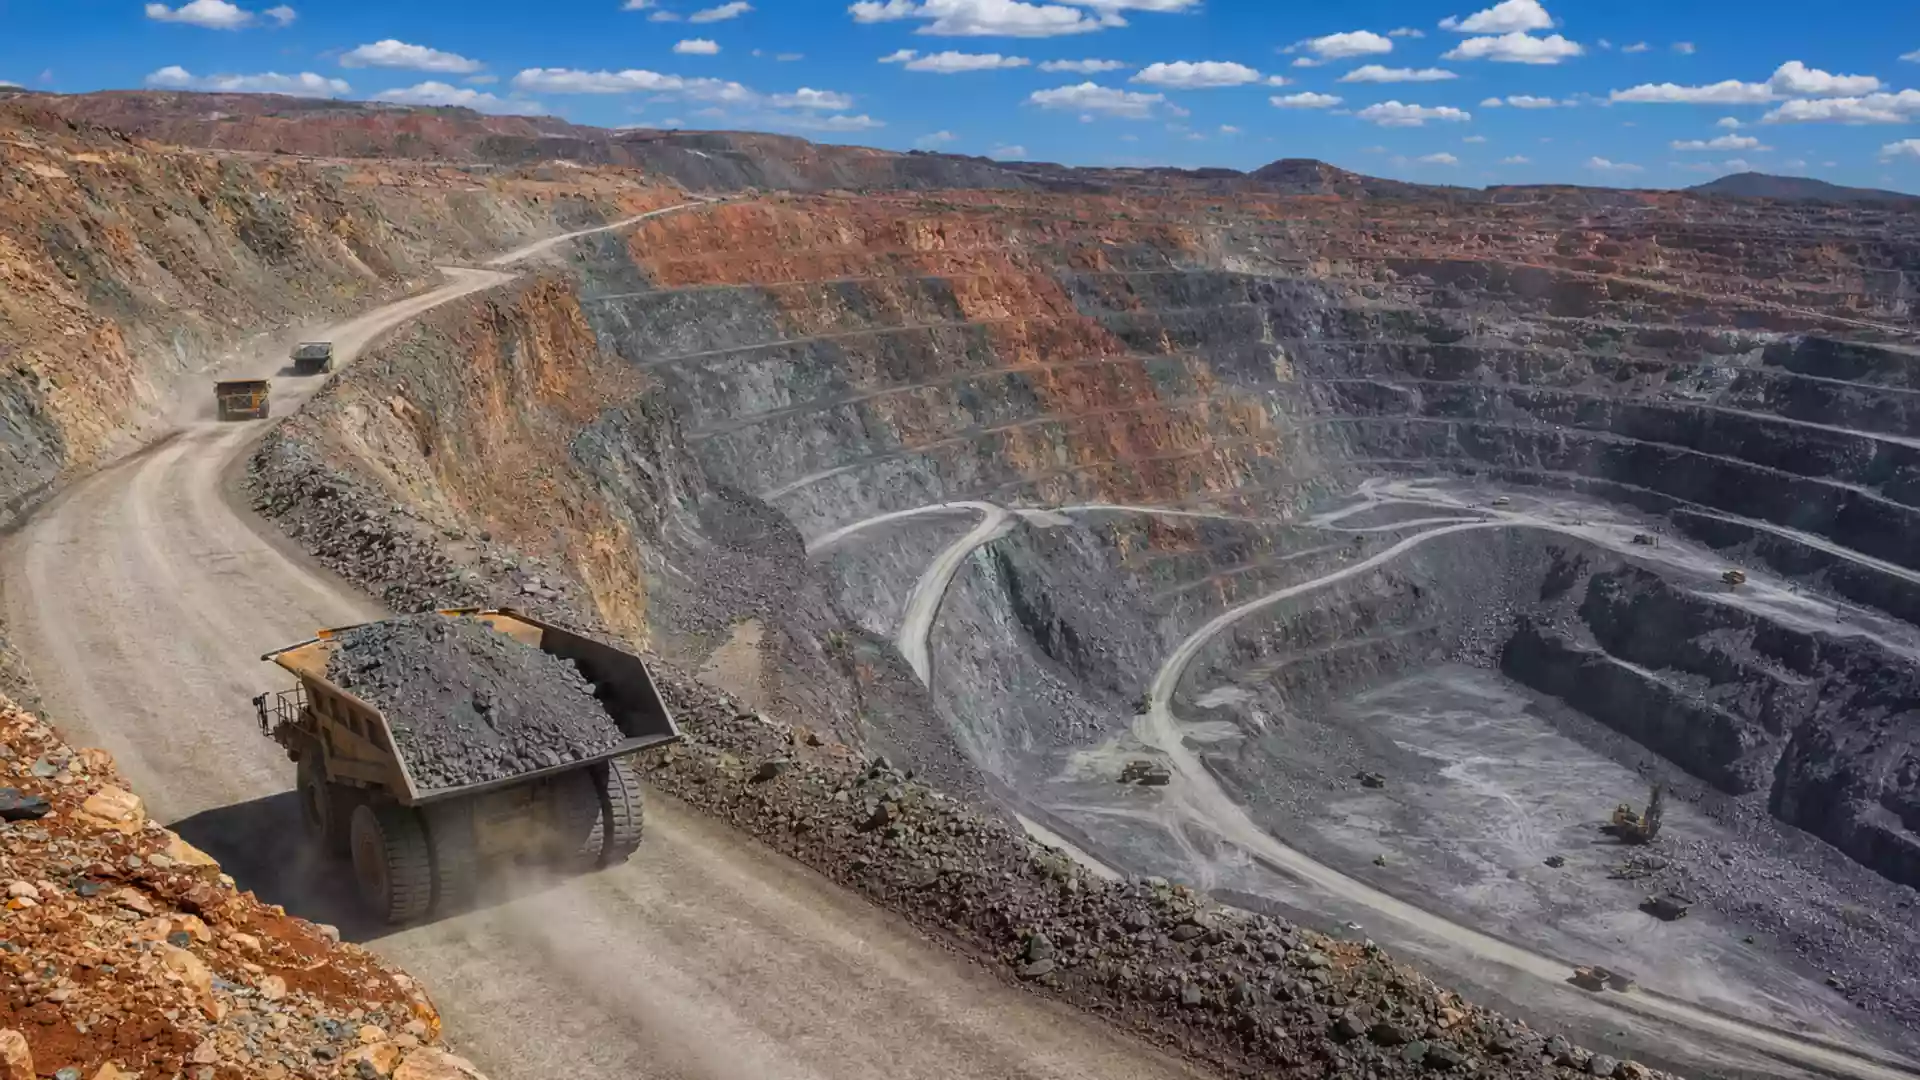
The shipment was confirmed by CEO Lewis Black on October 24, when he reported a single container dispatched to a customer. It marks the first commercial delivery from Sangdong in over 30 years, a genuine operational milestone for a project that has spent years in development.
A Delivery and a Timetable Are Not the Same Question
Five days before Black's announcement, on October 19, Almonty used its investor day to update expected delivery timing for Phase I and Phase II of the Sangdong build-out. Press coverage linked those revised expectations to the stock's recent weakness — a connection that cannot be pinned down as the sole cause.
That distinction matters more than it might appear. A completed shipment answers whether ore is moving; the delivery schedule answers whether it is moving at the pace the company previously promised. A miner can notch a significant first and still fall behind its own earlier guidance, and conflating the two muddies rather than clarifies the picture.
Treating the initial container as a rebuttal to every doubt about the timeline, then, overshoots. It is evidence of execution, not a substitute for tracking how Phase I and Phase II actually progress against the updated plan.
Should investors sell immediately? Or is it worth buying Almonty?
The Raise: 20.7 Million Shares at US$6.25
The financing side tells a similar story of progress that stops short of proof. Almonty sold 20,700,000 common shares at US$6.25 apiece, including the fully exercised over-allotment option, for gross proceeds of US$129,375,000.
Two words in that sentence deserve weight: "gross" and "shares." The capital arrives through newly issued equity, so the added financial room comes with a larger share count. The placement by itself does not answer what the stock is worth per share — it only establishes that the company now has more room to maneuver.
Management has earmarked the proceeds for exploration and project development, mine expansion, and working capital and general corporate purposes. That is a wide mandate, and investors should not read it as an operating result already in hand. Capital creates options; it does not replace economic success.
B. Riley Keeps Its Buy, Cuts Its Number
On October 27, B. Riley Securities reiterated its Buy rating on Almonty while lowering its price target to US$20 from US$25, according to media reports. A buy call and a reduced target are not contradictory — they mark the gap between confidence in the company's direction and the price an analyst is willing to pay for it.
The combination is instructive precisely because it is not a full reversal. The rating held; the valuation came down. What the sources do not provide is a specific reason for the cut, so investors are left to read the two signals separately: a positive investment verdict does not freeze the assumed valuation, and a lower target does not by itself invalidate the growth story.
Neither celebrating the Buy label in isolation nor treating the target cut as a verdict against Almonty gets at what is actually informative — the tension between the two.
What to Watch From Here
The through-line across both developments is translation: funded expansion into economic value, and first shipments into a delivery cadence that matches expectations. Almonty now has both the capital and a tangible export to its name. What remains open is whether subsequent deliveries track the schedule laid out on October 19, and whether the proceeds turn into mine development rather than simply sitting on the balance sheet.
For investors, the sensible split is this: the October 24 container is a real sign of implementation, and the October 27 note is an analyst's assessment rather than a fixed corporate value. The stock's recent softness proves neither failure nor the insignificance of the shipment. The next deliveries, measured against the communicated timeline, will carry more weight than either headline on its own.
Ad
Almonty Stock: New Analysis - 4 November
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.