Almonty: Sangdong Is Running, but the Cargo Still Has to Sail
Published on 10/21/2026 at 17:21 | Editorial boerse-global.de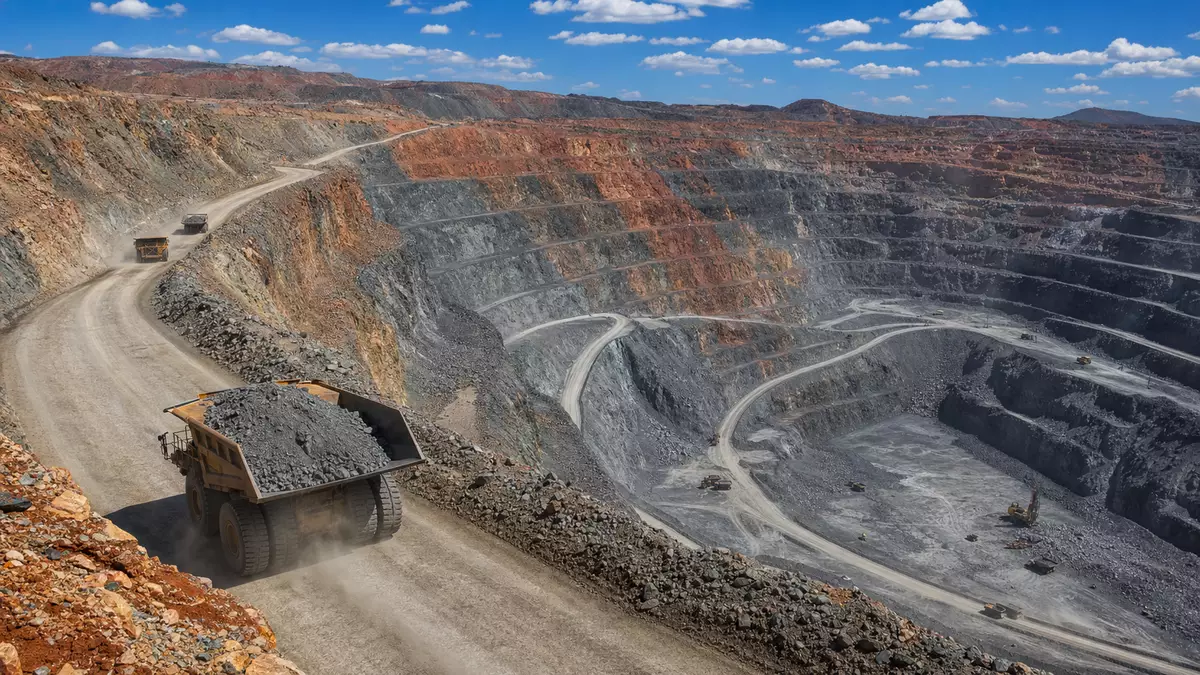
A mine in operation and a reliable shipping schedule are two different things. That distinction sits at the heart of the Almonty story right now, and the 4.2% gain in the share price on the day does nothing to settle it. Anyone weighing the outlook should pay less attention to status announcements and more to how they are executed on the ground.
At Monday's investor day, Almonty declared Sangdong commercially operational and said the second expansion phase is advancing. Those are encouraging statements about project progress. What they do not answer is the question investors care about just as much: when does that progress actually show up in shipments?
Stifel trims its target but keeps the buy
That is precisely where yesterday's assessment from Stifel lands. Analyst Brock Cannon cut his price target to US$21 from US$25 while leaving the rating at Buy. Following the investor day, the firm pushed back its assumptions for shipments from both of Sangdong's expansion phases.
Read together, the two developments carry a warning against equating project milestones with on-time delivery. The buy call stands; the timeline has nonetheless grown more cautious. Positive long-term conviction and near-term recalibration can coexist — that tension, rather than any contradiction, is the crux of the valuation case.
The line between company disclosure and analyst model also matters here. Almonty reported commercial operations and expansion progress. Stifel responded by adjusting its delivery assumptions. Nothing in that sequence suggests the operating status has been walked back — and equally, the company's announcement should not be read as proof that every expectation for the shipment ramp has already been met.
Should investors sell immediately? Or is it worth buying Almonty?
Cash, cargo and a falling tungsten price
The balance sheet tells its own part of the story. At the same investor day, the finance chief put the cash position at the end of the second quarter of 2026 at CAD 1.2 billion. That is a meaningful figure for framing the company's financial room to manoeuvre — but it describes a past balance-sheet date, not today's account, and it answers a different question from the one about the pace of operational progress.
A sector report published yesterday flagged a stiff headwind: Chinese APT prices have fallen almost 70% from their mid-March highs, putting Almonty's development in a tougher tungsten market. The decline does not translate directly into a matching change in company revenue, nor does it offer a clean explanation for the share price. Commodity quotes, delivery progress and equity valuation operate on separate levels, and conflating them turns a genuine risk factor into a premature catch-all answer.
Which is why the cash cushion deserves attention without becoming a universal argument. Liquidity can open up financial options; it is no proof that production and shipping plans have been fulfilled. By the same token, a weaker commodity market does not automatically invalidate operational progress.
A booking is not a shipment
On Sangdong itself, CEO Lewis Black said on 7 October that the plant is in operation. The company added that the first concentrate shipment is booked for 24 October. A booking remains a booking — it is not the same as a completed sailing.
That gap between announcement and execution is where investors should focus. The reported cash balance speaks to the financial starting position. The booked cargo speaks to the next operational step. The price slump speaks to the market environment. Short-term supply programmes at Los Santos and in Rwanda round out the operating picture and are worth watching precisely because they shift the spotlight away from Sangdong alone — though they are no evidence that a later start to deliveries there would be fully offset in economic terms.
Weighing it all up, the appropriate stance is a measured one. The progress justifies attention, not yet a leap of faith that execution will run smoothly. What would make the case more convincing is not another positive label but alignment between announced progress and actual delivery performance. Commercial operation is an important step toward that — not the final proof.
Ad
Almonty Stock: New Analysis - 21 October
Fresh Almonty information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.