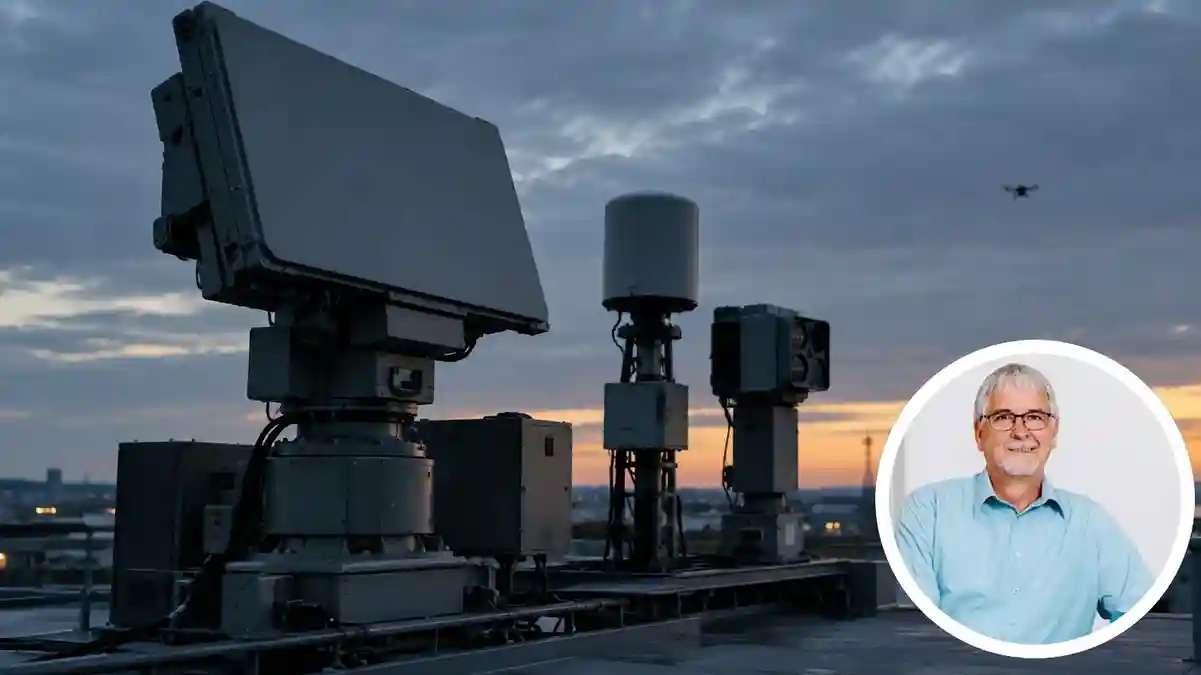
DroneShield's Record Top Line Meets a A$32.2 Million Loss — and an Air Force Kit Gap
Published on 11/14/2026 at 15:51 | Editorial boerse-global.de
DroneShield shares fell 4.1% on the ASX yesterday as risk aversion swept through the Australian market, hitting smaller companies and volatile growth names hardest. The retreat came against a backdrop that has become familiar to holders: blockbuster revenue on one side of the ledger, a statutory loss on the other.
The company booked record first-half 2026 revenue of A$125.8 million, yet reported a statutory net loss after tax of A$32.2 million for the same period. That pairing sits at the heart of the debate over the counter-drone specialist, whose order book is swelling faster than its bottom line.
Committed revenue lands inside guidance
For the full 2026 financial year, DroneShield has put committed revenue at A$261 million, measured as of 12 October and disclosed in an update on 15 October. That figure falls within the company's own revenue guidance range of A$250 million to A$270 million — a detail drawn from an analysis of the October update published on Tuesday.
The committed-revenue number gives the bullish case something concrete to stand on. If those pledges convert into booked sales, the company's full-year plan looks reachable. What the figure does not settle is how profitably that volume can be delivered.
Should investors sell immediately? Or is it worth buying DroneShield?
An Air Force solicitation with a caveat
Separately, the US Air Force on Tuesday issued a solicitation for equipment needed to operate DroneShield Immediate Response Kits at Joint Base San Antonio. The tender follows the Air Force's finding that the kits were missing essential components. The procurement covers equipment for running the kits at that location, with the service branch seeking the supplementary parts through the advertised process.
Why the margin question refuses to go away
The loss alongside record revenue keeps earnings quality in the spotlight. A more favourable reading of the stock would rest on additional sales arriving with better profitability — investors betting on a rebound are effectively underwriting exactly that improvement. Should higher volume fail to move the earnings needle, the revenue story loses much of its force as an argument for the shares.
Market conditions can compound the pressure. Yesterday's risk-off tone fell particularly on smaller firms and high-beta growth stocks, meaning an operational improvement may matter all the more if caution persists.
DroneShield at a turning point? This analysis reveals what investors need to know now.
What the next catalyst needs to show
Committed revenue provides a tangible anchor for the positive view as long as it continues to support the annual plan. Pair that with stronger profitability and a more durable recovery scenario comes into view. Leave earnings weak, and margin pressure is likely to keep driving investor decisions.
Fresh disclosure on revenue conversion and earnings progress therefore looms as the next substantive catalyst. The test is how the two fit together: confirmation of the sales outlook would carry real weight only if DroneShield simultaneously shows headway toward better results.
Ad
DroneShield Stock: New Analysis - 14 November
Fresh DroneShield information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.