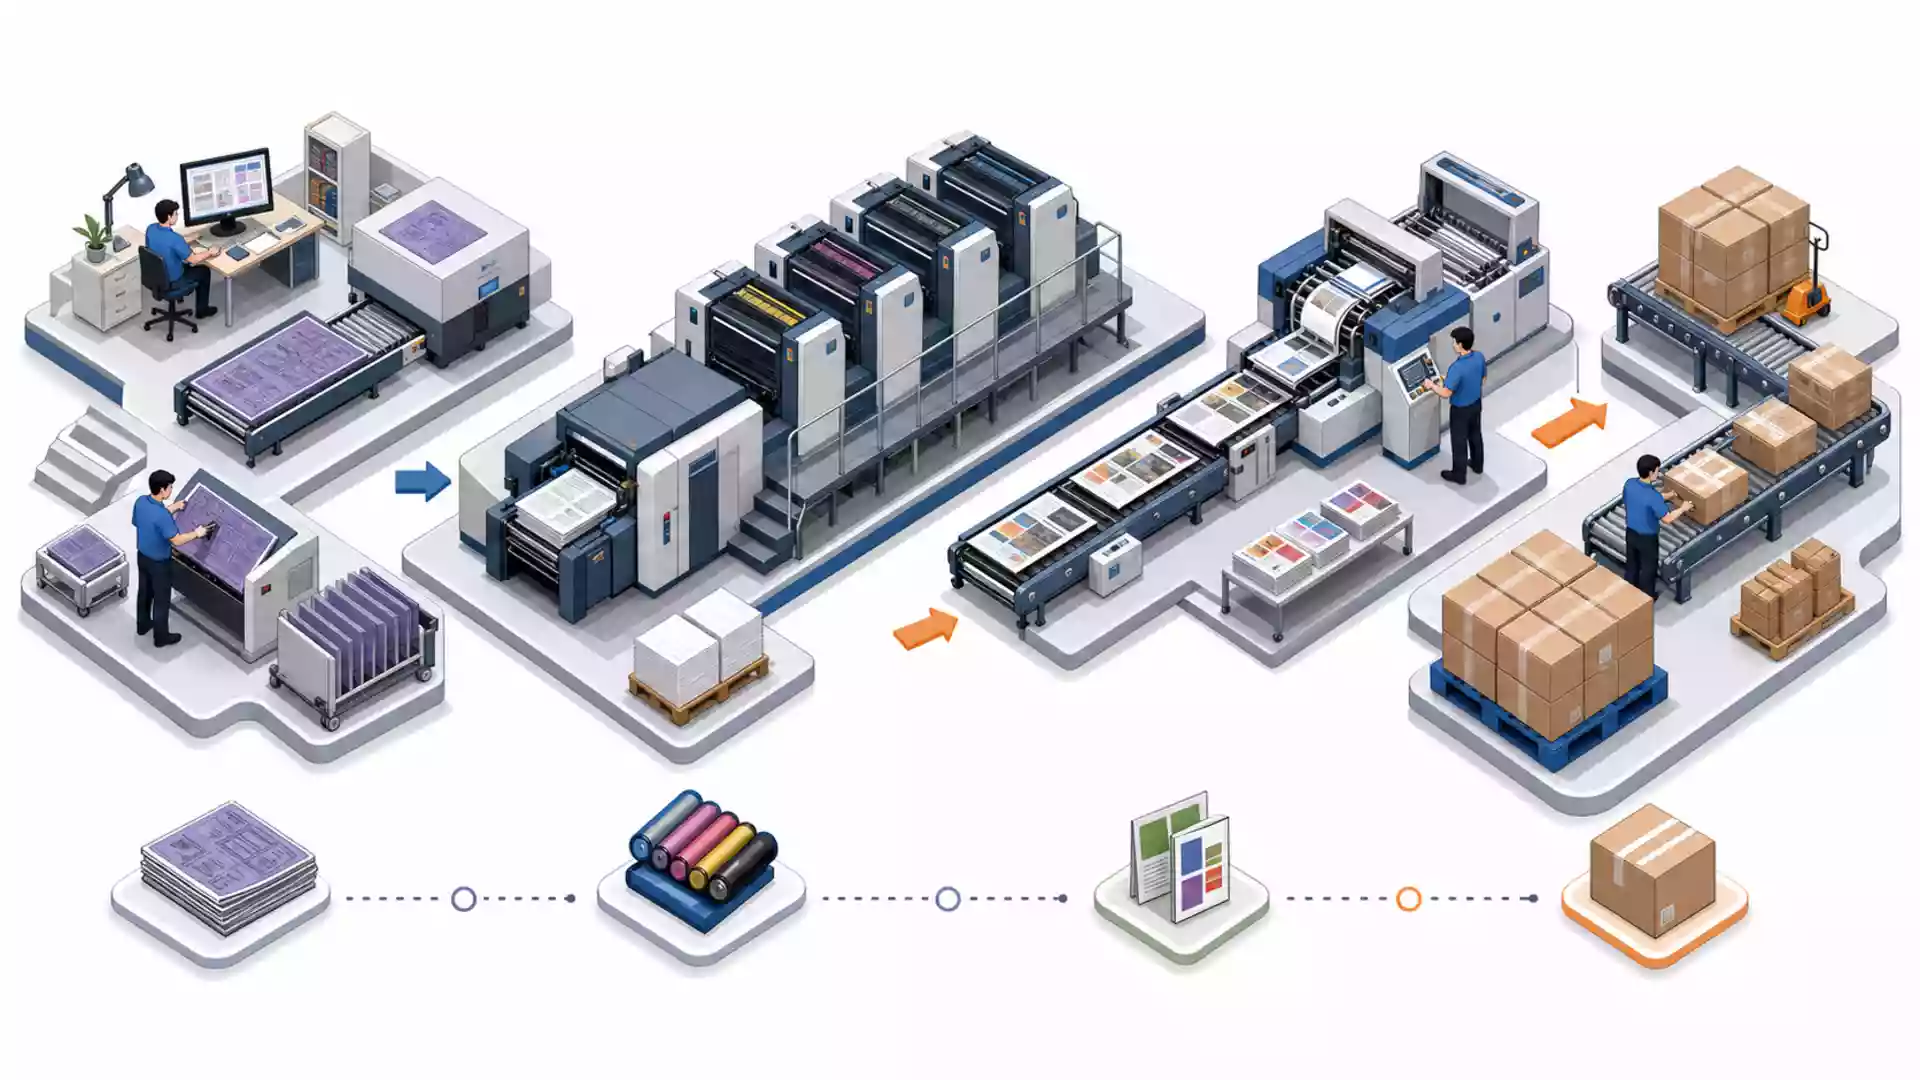
Heidelberg Druck's Order Book Is Fattening — Its Bottom Line Is Not
Published on 11/14/2026 at 03:20 | Editorial boerse-global.de
Heidelberger Druckmaschinen is booking more business than it was a year ago. Turning that into profit is proving to be the harder half of the job.
The German press manufacturer pulled in EUR 604 million of orders in the second quarter of fiscal 2026/2027, up from EUR 551 million in the same period a year earlier. Across the first six months, incoming orders reached EUR 1.14 billion. Revenue, however, moved the other way: quarterly sales slipped to EUR 509 million from EUR 519 million, and the half-year top line fell to EUR 913 million from EUR 985 million.
The margin picture is starker still. Adjusted EBITDA as a share of sales came in at 3.7% for the half, less than the 6.4% recorded a year earlier — a near-halving of profitability at the operating level.
What management blames
Heidelberg points to a combination of external and internal drags. Geopolitical crises, delayed projects and adverse product-mix effects all weighed on the result, with the mix issues tied specifically to developments in the Middle East. The project slippage was concentrated in the Technologies segment. Management has also flagged the broader global economic climate and persistent cost pressure as reasons for trimming its guidance.
Should investors sell immediately? Or is it worth buying Heidelberger Druckmaschinen?
That guidance, first adjusted on 29 October, now targets a full-year adjusted EBITDA margin of 5.6% to 6.6% on broadly stable sales. Hitting it would require a marked second-half improvement on the 3.7% delivered so far — a step-up the company insists is achievable.
Two customers, one message
The order intake is being driven in part by packaging clients retooling their operations. LPI is investing in a Speedmaster XL 106 and, according to Heidelberg, is evolving from a converter into a packaging producer. Brazilian packaging specialist Macron Indústria Gráfica has ordered a Speedmaster CX 104 — a customer Heidelberg places squarely within its integration of manroland sheetfed, along with the wider product and service range that acquisition brings.
Those wins carry weight only if they convert into profitable revenue. For investors, the question is less whether customers are ordering than whether Heidelberg can translate that demand into stronger sales and a healthier margin.
Market reaction
The stock has felt the disappointment. Shares fell 3.2% in one session and were down a further 3.1% the next, as the market digested the gap between a growing backlog and a shrinking profit base.
Heidelberg will publish third-quarter figures for fiscal 2026/2027 on 16 February 2027 — the next real test of whether the order book can be turned into earnings.
Ad
Heidelberger Druckmaschinen Stock: New Analysis - 14 November
Fresh Heidelberger Druckmaschinen information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.