
Hochtief's Order Engine Keeps Firing Even as the Stock Takes a Breather
Published on 09/20/2026 at 08:40 | Editorial boerse-global.de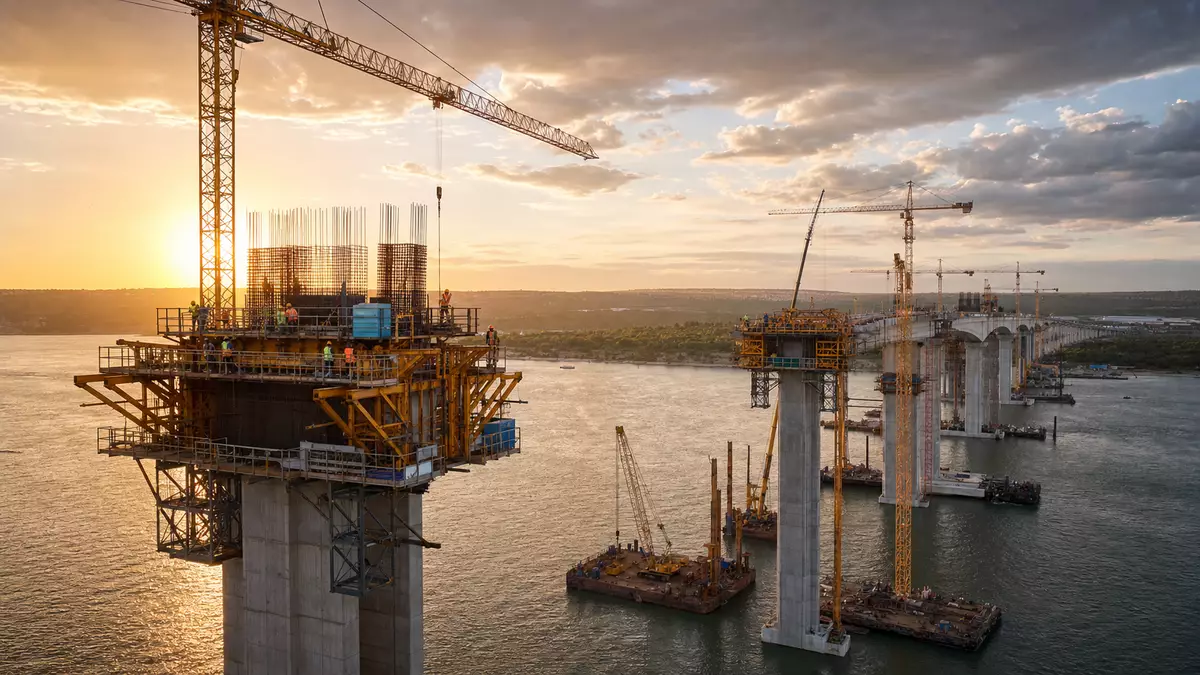
Hochtief's Australian arm shows no sign of slowing down. On Thursday, subsidiary CPB Contractors landed the contract to build the East Perth Primary School in Western Australia — the latest in a rapid-fire string of wins that also includes a solar-and-battery project delivered through UGL, roughly AUD 250 million for upgrading the Kwinana Freeway, and a data centre build in India via Leighton Asia.
That steady flow of new work speaks to resilient demand across the group's international heartlands. Yet the equity tells a different story. Hochtief shares closed Friday at EUR 394.60, leaving them 29% below the 52-week high of EUR 554.50 touched back in May. Even so, the stock is still up 18% since the start of the year — a gap that captures the tension investors are now wrestling with: solid operating momentum on one side, a cooling chart on the other.
A strategic pivot toward energy infrastructure
While the order announcements pile up, Hochtief has been quietly repositioning itself toward higher-margin territory. Roughly two weeks ago the Essen-based builder acquired Autmatec, a German power-grid specialist with about 80 skilled staff and annual revenue of around EUR 50 million, folding it into its European energy-infrastructure business.
The move is part of a broader push into electricity transmission. At the end of August, Hochtief also secured a stake in a project to reinforce London's power network. And alongside its Spanish majority owner ACS, the group retained its position atop ENR's global ranking of international contractors. Management is betting that the worldwide scramble for transmission lines will deliver dependable, multi-year project pipelines — a cushion against the cyclicality of traditional construction.
Margins, not just volume, are the real test
The pivotal question for the share price is whether Hochtief can convert its swollen backlog into profit. At the mid-year mark for 2026, the company reported a record order book of EUR 84.8 billion, up 23% year on year.
Should investors sell immediately? Or is it worth buying Hochtief?
A fat pipeline alone guarantees nothing if unforeseen cost inflation or delays on large projects eat into returns. So far, operations have held up well. First-half 2026 operating profit climbed 35% to EUR 480 million, with revenue advancing 10% to EUR 20.1 billion.
To justify its valuation over the longer haul, Hochtief needs to show in coming quarters that the new work in energy infrastructure, digitalisation and transport can be executed at margins comparable to recent projects delivered by its US subsidiary Turner.
Raised guidance rests on a growing backlog
The bull case hinges on the group hitting — or beating — the upgraded targets it set out at the end of July. Hochtief now guides toward full-year 2026 operating profit of EUR 1,025 million to EUR 1,100 million, lifted from an earlier range of EUR 950 million to EUR 1,025 million. That would mark an increase of 30% to 40% over the prior-year figure.
Much of that optimism traces back to Turner, whose profit forecast was raised to USD 1,400 million–1,460 million. If Hochtief can simultaneously scale its activities in data centres and renewable energy, the recent pullback could quickly look overdone. With demand intact across North America and Asia-Pacific, the group has a broad base from which to grow operating cash flow and cement its leadership in technically demanding construction segments.
Cost risks and a softening economy cut the other way
The bear case is hardly empty. Global construction remains exposed to material shortages, geopolitical disruption and shifting financing conditions for large commercial clients. Any hiccup on complex data-centre builds or sprawling infrastructure schemes could trigger substantial cost overruns and margin erosion.
Chart watchers have also turned cautious. According to media reports, the stock slipped below its widely followed 200-day moving average in September, triggering additional selling. With the shares currently 6.6% below that average, negative momentum risks becoming entrenched. Should doubts grow about whether Hochtief can reach the upper end of its guidance in the second half, selling pressure could persist and further erode the gains of the past twelve months.
November's interim report is the next real catalyst
Direction from here is unresolved. As long as the stock can defend the area around its recent lows, a stabilisation remains possible. A sustained break below prior support, however, would open the door to a deeper correction toward lower valuation levels.
The next major catalyst is already on the calendar: on 5 November 2026, Hochtief will publish its interim report for the first nine months of the year and discuss the figures in an analyst conference. Until then, fresh contract awards and the stability of the interest-rate environment will determine whether investors re-embrace the operating records or keep their focus on the risks embedded in the construction sector.
Ad
Hochtief Stock: New Analysis - 20 September
Fresh Hochtief information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


