
Micron's Sold-Out Memory Bet Meets Its Toughest Test: A 99% Strike Mandate in Taiwan
Published on 10/09/2026 at 15:11 | Editorial boerse-global.de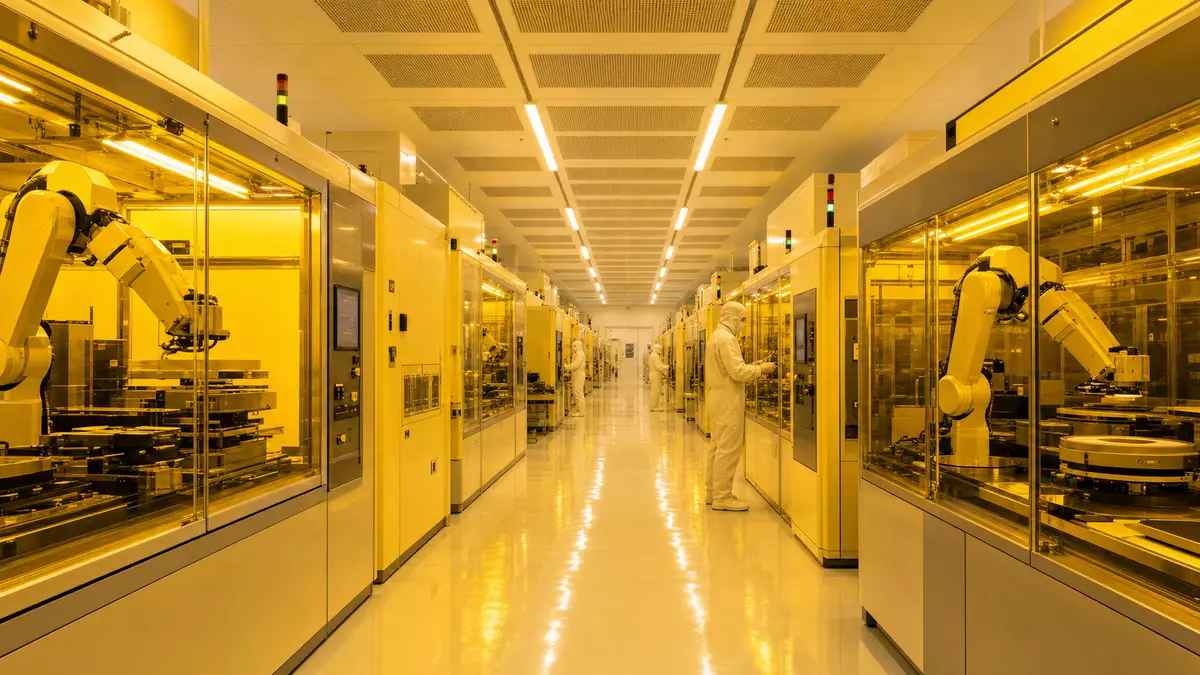
The bottleneck in modern computing has migrated. For years, the industry fixated on the raw horsepower of GPUs and CPUs, but the real constraint now sits in the memory banks — and that shift has turned Micron Technology from a commodity supplier into one of the most strategically positioned players in the AI supply chain.
The numbers tell the story of that transformation. In its fiscal fourth-quarter 2026 report, the US memory specialist posted record revenue of $54.23 billion, with full-year 2026 sales climbing to $133.19 billion. Adjusted earnings per share for the quarter reached $33.42. Management isn't slowing down: for the first quarter of fiscal 2027, it's guiding toward $61.5 billion, give or take $1.5 billion.
That kind of trajectory has drawn fresh conviction from the analyst community. Gil Luria of D.A. Davidson raised his price target from $2,100 to $3,000 while reaffirming a buy rating, arguing that demand for high-performance memory will outstrip global supply not just next year but through 2027 and 2028. His case rests on something more concrete than optimism: capacity for the advanced HBM4 generation is already sold out for 2026. Hyperscalers and server makers, in his reading, are locking in manufacturing allotments at nearly any price, terrified of being left short.
A New Module, and a Widening Moat
Micron is also preparing a next-generation module aimed at bridging the long-standing trade-off between memory capacity and speed. Volume production is slated for the second half of 2027. For data-center operators, the payoff is density — more capacity in less space, lower energy consumption, and faster data flows. That's precisely the kind of engineering leverage that keeps high-bandwidth memory as the chokepoint of modern data centers, even as standard components ride out cyclical dips.
Should investors sell immediately? Or is it worth buying Micron Technology?
The pricing power shows up in the margins. Micron's gross margin hit 87% in the most recent quarter — a level, as Luria put it, that most industries can only dream about.
Labor Friction at the Factory Floor
Yet the same explosive growth that fuels those margins is generating friction at the production base. At the Taoyuan union in Taiwan, 1,994 members voted to authorize a strike — a 99% approval rate among those voting. The dispute centers on the company's bonus system, with workers demanding a permanent 15% share of operating profit. No date has been set for any potential walkout.
The stakes are hard to overstate. More than half of global chip fabrication takes place on the island, and advanced memory production relies on a tightly interconnected web of specialized sites. Even limited work stoppages can trigger delays in finely calibrated supply chains that ripple out to customers worldwide. Still, the conflict reads less like an operational threat than a distribution fight born of soaring profits — workers demanding their slice of an exceptional boom. Even if management concedes financially, margins are likely to stay at levels that leave rivals envious.
Dividends, Drawdowns, and the Road Ahead
Alongside its heavy investment program, Micron is working to keep shareholders onside. The company declared a dividend of $0.15 per share for the past quarter, payable October 29 to investors on the register as of October 14.
The stock, meanwhile, is absorbing the crosscurrents. In recent trading it climbed 1.9% to EUR 941.30, leaving it roughly 15% below its 52-week high of EUR 1,103.80 — a gap that suggests recent headlines have left a mark. Reports of softer revenue expectations from AI frontrunners, combined with the Taiwan labor standoff, have given some investors pause about the durability of the boom.
For those watching the fundamentals rather than the tape, the picture looks different. As long as demand for computing power exceeds the physically manufacturable supply of specialized memory chips, pricing power stays intact. A combination of massive pre-orders, sold-out HBM production, and a solid balance sheet gives Micron a resilience that much of the market, in Luria's view, is currently underestimating. The present consolidation may, in hindsight, look like a healthy waypoint in a multi-year supercycle — provided the company can keep its factories running smoothly.
Ad
Micron Technology Stock: New Analysis - 9 October
Fresh Micron Technology information released. What's the impact for investors? Our latest independent report examines recent figures and market trends.


